True portfolio resilience isn’t about owning more properties; it’s about engineering a balanced system of non-correlated assets.
- Geographic diversification only works if regions have different economic drivers to protect against specific shocks, not just general downturns.
- A deliberate 60/40 split between cashflow-focused assets (like HMOs or commercial property) and capital-growth assets creates long-term stability and income.
Recommendation: Actively manage your portfolio by regularly identifying and exiting the bottom 20% of underperforming properties to continuously upgrade overall quality and resilience.
For many UK investors, a property portfolio is something that happens by accident rather than by design. An initial investment, followed by another, and soon you have a collection of assets. But is it a portfolio or just a pile? The common advice to “diversify” often translates to simply buying in a different postcode, a strategy that offers little protection when a broad economic wave hits. This approach treats diversification as a box-ticking exercise rather than the strategic imperative it truly is. The result is often a portfolio that is geographically scattered but economically concentrated, leaving it vulnerable to the very risks diversification was meant to mitigate.
The shift from an accidental landlord to a strategic portfolio engineer begins with a change in mindset. It’s about moving beyond simply acquiring properties and instead focusing on constructing a resilient financial ecosystem. True diversification isn’t about location alone; it’s a multi-layered strategy involving a deliberate blend of asset types, income profiles (cash flow vs. capital growth), and, most critically, exposure to genuinely non-correlated economic drivers. The key isn’t asking “Where should I buy next?” but rather “What specific risk does my portfolio currently face, and which asset can I add to counterbalance it?”.
This guide provides a framework for that strategic construction. We will deconstruct the layers of effective diversification, moving from high-level regional allocation to the granular detail of asset selection and performance management. This is the blueprint for transforming an accumulated collection of properties into an intentionally designed, robust portfolio built for long-term resilience and returns.
To navigate this strategic approach, this guide breaks down the essential components of portfolio engineering. The following sections provide a detailed roadmap for assessing and constructing a truly diversified UK property portfolio.
Summary: A Strategic Framework for UK Property Portfolio Construction
- Why Investors With Properties in 3+ UK Regions Weathered 2008 With 40% Less Loss
- How to Split Your Portfolio: 60% Cashflow Properties and 40% Capital Growth
- Add Commercial Property or More Residential: Which Diversifies a 5-Property Portfolio
- The 6-Property Newcastle Portfolio That Lost 35% Value When Shipyards Closed
- How to Identify and Exit Your Worst-Performing 20% to Upgrade Portfolio Quality
- Capital Appreciation vs High Yield: Which Strategy Suits Your 15-Year Plan
- London Zone 2 vs Commuter Towns vs Rural: Which Location Type Delivered Best 20-Year Returns
- Which Property Investment Model Suits Your Income, Time, and Risk Tolerance
Why Investors With Properties in 3+ UK Regions Weathered 2008 With 40% Less Loss
The 2008 financial crisis serves as a stark lesson in the difference between superficial and strategic geographic diversification. Investors who simply owned properties in London, Birmingham, and Manchester found their portfolios were highly correlated, as all were exposed to the same macroeconomic shock. True resilience, however, came from investing in regions with genuinely different economic drivers. The variance in recovery times was dramatic; post-crash regional recovery data shows that London recovered its 2007 price peak by April 2012, while the North East took until January 2021. This nine-year gap highlights that a “national” housing market is a dangerous myth.
This phenomenon is explained by what economists call “non-correlated risk.” A portfolio balanced between, for example, a university city with a stable public sector and student rental market, a logistics hub driven by e-commerce, and a coastal town reliant on tourism, is insulated against a shock that affects only one of those sectors. An academic study on regional economic spillovers confirms this, noting a distinct North-South divide where northern regions often act as net receivers of house-price shocks. The research supports the case for building a portfolio across cities with genuinely different economic fundamentals, not just different postcodes. This is the essence of portfolio engineering: consciously selecting assets whose performance is unlikely to rise and fall in perfect unison.
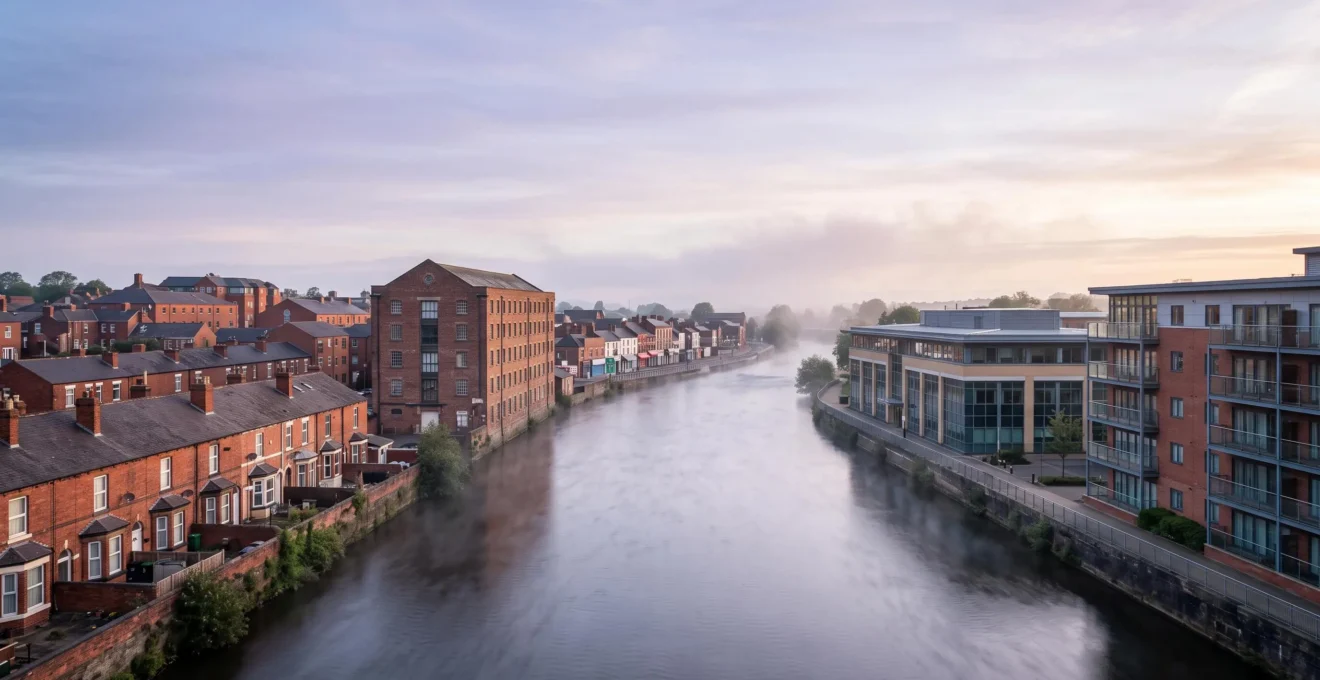
The image above captures this contrast perfectly: the industrial past on one bank and a modern residential and leisure economy on the other. A portfolio split between these two “worlds” would have a natural hedge. The goal isn’t to predict the future but to build a portfolio that is robust enough not to have to. By spreading risk across fundamentally different local economies, investors can significantly dampen the impact of regional or sector-specific downturns, creating the stability needed for long-term growth.
How to Split Your Portfolio: 60% Cashflow Properties and 40% Capital Growth
Beyond geography, the most critical layer of diversification is the strategic split between assets acquired for cash flow and those for capital growth. Many investors fall into the trap of seeking both from a single property, an often-elusive goal. A more robust approach is to engineer a portfolio where different properties serve different functions. The 60/40 split is a well-regarded model: 60% of the portfolio is dedicated to high-yielding, cash-flow-positive assets that cover costs and provide income, while 40% is in high-demand areas with lower yields but strong potential for long-term capital appreciation.
This strategic blending ensures the portfolio is self-sustaining. The cash flow from assets like Houses in Multiple Occupation (HMOs) or properties in high-yield northern cities can service the debt on the lower-yielding, growth-focused properties in the South East or prime city centres. The yield difference can be significant; landlord association data shows the average UK buy-to-let yield is around 5.8%, while HMOs can achieve 7.0% or more. This surplus cash flow provides a crucial buffer during void periods or economic downturns, preventing the need for a forced sale of growth assets at an inopportune time.
Ultimately, this isn’t just an allocation strategy; it’s a risk management tool. A portfolio heavily skewed towards capital growth is vulnerable to interest rate rises and can become a cash drain. A portfolio focused solely on high yield may miss out on significant wealth creation from market appreciation. The 60/40 blend provides a balanced engine for growth, funded by its own internal cash generation, creating a system that is far more resilient to market volatility than one pursuing a single objective.
Your Action Plan: Building a Balanced Cashflow and Growth Portfolio
- Deliberate Mixing: Accept that no single property is both high-yielding and high-growth. Actively seek out a mix of lower-cost, higher-yield assets to complement your lower-yield, higher-growth properties.
- Strategy Blending: Combine different rental strategies such as standard single lets, HMOs, and serviced accommodation. This ensures that seasonal or void-driven cash flow dips in one asset class are offset by steady income from others.
- Periodic Review: Regularly review the portfolio’s overall performance. A larger, more varied portfolio can absorb a single void period far more effectively than a small, concentrated one. Assess if the 60/40 balance is being maintained.
- Future-Proofing: Treat diversification as continuous protection against market shocks, regulatory changes (like EPC ratings), and shifting tenant demand, not just a one-off allocation decision made at the point of purchase.
Add Commercial Property or More Residential: Which Diversifies a 5-Property Portfolio
For an investor with an existing residential portfolio, the next diversification frontier is often the leap into commercial property. While it may seem daunting, adding a commercial asset can be a powerful move for genuine risk reduction and yield enhancement. The residential and commercial markets are driven by different forces; residential is influenced by wages, interest rates, and social trends, while commercial is tied to business confidence, consumer spending, and specific industry performance (e.g., logistics vs. high street retail). This lack of correlation is a diversifier’s dream.
The yield differential is a primary motivator. As peer-to-peer real estate market analysis shows, the average yield in the residential sector is around 4.1%, compared with an average of 6.5% for commercial property, with some industrial units yielding much more. Furthermore, commercial leases are typically far longer (10-25 years vs. a 12-month AST) and often come with Full Repairing and Insuring (FRI) terms, meaning the tenant is responsible for all costs, including structural repairs. This provides a level of long-term, passive, and predictable income that is difficult to achieve in the residential space. This trend is gaining traction, with recent lender data showing a 31% year-on-year rise in applications for semi-commercial property purchases, reflecting a strategic pivot among professional landlords.
The following table, based on a comparative analysis from YouTrust, breaks down the key differences for an investor considering this strategic move.
| Metric | Residential Buy-to-Let | Commercial Property |
|---|---|---|
| Typical gross yield | 3-6% | 5-12% (8%+ for industrial/retail warehouses in strong locations) |
| Typical lease length | 6-12 month AST | 10-25 years, often with FRI (Full Repairing and Insuring) terms |
| Capital appreciation driver | Broader housing market trends (~4-6% p.a. over the past decade) | Sector-specific demand (e.g. industrial/logistics, e-commerce) |
| Typical minimum direct investment | Standard BTL mortgage deposit | £200,000+ direct, or £1,000-£50,000 via funds/REITs |
For a 5-property residential portfolio, adding a sixth commercial property is not just adding another asset; it is introducing an entirely new set of risk-and-return characteristics, significantly strengthening the entire portfolio’s resilience.
The 6-Property Newcastle Portfolio That Lost 35% Value When Shipyards Closed
The cautionary tale of a hypothetical but all-too-plausible Newcastle portfolio illustrates the critical flaw in naive diversification. Imagine an investor in the 1970s who diligently built a portfolio of six properties across different Newcastle suburbs. On paper, they were diversified. In reality, every single one of those assets was economically tethered to the health of the Tyne shipyards. When the industry collapsed in the 1980s, it wasn’t just shipyard workers who lost their jobs; the entire local economy faltered. Tenant demand evaporated, and property values plummeted across the board. The investor’s “diversified” portfolio fell in near-perfect unison.
This scenario highlights the most overlooked aspect of risk management: single-industry exposure. Owning six properties in a town dominated by one large employer (be it a factory, a military base, or a university) is arguably riskier than owning two properties in two different cities with entirely separate economic drivers. The National Residential Landlords Association (NRLA) correctly states that diversification “smooths the impacts of tenant voids and unexpected maintenance bills,” but this protection only holds if the risks are not systemic to the entire portfolio.
The lesson is not to avoid Newcastle, which has since brilliantly reinvented its economy. The lesson is to actively analyse the economic underpinnings of your chosen locations. A truly strategic portfolio might have included one property in Newcastle (leveraging its new tech and service industries), one in a university town like Cambridge, one in a logistics hub like Northampton, and one in a tourism-driven city like Bath. Such a portfolio would be insulated from the decline of a single industry, as the economic fortunes of these cities are not directly linked. This is the difference between owning a collection of buildings and engineering a resilient investment portfolio.
How to Identify and Exit Your Worst-Performing 20% to Upgrade Portfolio Quality
A core discipline of strategic portfolio management, often termed “portfolio hygiene,” is the regular and dispassionate culling of underperforming assets. Many investors treat property as a “buy and hold forever” asset, but this can lead to a portfolio cluttered with “zombie” properties that drain cash, time, and opportunity. A professional strategist actively identifies the bottom 10-20% of their portfolio and makes a clear-headed decision: improve or exit. This process releases capital and management capacity to be redeployed into higher-quality or more strategically-aligned assets.
Identifying the “worst” performers requires a multi-faceted analysis beyond just headline yield. An underperforming asset might exhibit several of these traits:
- Low Total Return: Stagnant capital growth combined with a yield that is consistently below the market average for that property type and location.
- High Maintenance Overhead: An older property with persistent, costly issues (roof, damp, plumbing) that erode net income.
- Problematic Tenancy: High tenant turnover, frequent and long void periods, or a history of arrears or disputes that demand excessive management time.
- Negative Local Outlook: The property is located in an area with declining local infrastructure, rising crime rates, or the departure of a major employer.
The decision to sell can be emotional, especially if it was the first property purchased. However, the goal is to improve the overall health and performance of the portfolio as a whole. Selling a low-performing asset, even at a modest profit or small loss, can free up a deposit for a new property with significantly better prospects for both yield and growth, thereby upgrading the entire portfolio’s quality and future potential. This active management is what separates a passive accumulator from a proactive portfolio engineer.
Capital Appreciation vs High Yield: Which Strategy Suits Your 15-Year Plan
The debate between capital appreciation and high yield is not a question of which is “better,” but which is more aligned with an investor’s specific goals, time horizon, and risk tolerance. For a 15-year plan, the answer is rarely one or the other, but a dynamic blend that evolves over time. An investor in their early accumulation phase might prioritise capital growth to build a substantial asset base, while someone approaching retirement may pivot to maximise stable, high-yield income.
A growth-focused strategy involves targeting areas with strong fundamentals poised for appreciation, such as those with significant infrastructure investment (e.g., new transport links), demographic shifts, or regeneration projects. The trade-off is typically a lower initial rental yield. While long-run market data indicates that UK residential property has grown approximately 4-6% annually over the past decade, these assets can be a cash flow drain in the short term, requiring the investor to have sufficient income from other sources to cover mortgage and running costs. This strategy is a bet on the future value of an area.
Conversely, a yield-focused strategy prioritises immediate cash flow. This often means investing in less glamorous locations or more management-intensive assets like HMOs. This approach provides financial stability and covers all property costs from day one, but may offer limited capital appreciation. For a 15-year plan, a hybrid approach is often optimal. It might involve starting with growth assets for the first 5-7 years to build equity, then refinancing to extract that equity and reinvest it into high-yield properties to build income for the later stages of the plan. The key is to have a clear plan and not simply hope for the best of both worlds from a single asset.
London Zone 2 vs Commuter Towns vs Rural: Which Location Type Delivered Best 20-Year Returns
For decades, the default wisdom for growth-focused property investment was simple: buy in London. However, long-term data and recent trends paint a more nuanced picture, revealing a significant shift in performance away from urban centres towards their surrounding commuter belts. Astute investors now look beyond headline city names and analyse the performance of different *location types*. The post-pandemic world, with its emphasis on flexible working and quality of life, has accelerated this trend. Analysis shows that in many cases, commuter towns have provided superior total returns when factoring in lower entry costs and stronger recent growth.
The data is compelling. Recent house price comparison data shows that in every one of 12 major UK cities analysed, the surrounding commuter belt outperformed the urban centre. In the most striking example, prices in London fell 3.7% over the period studied, while its commuter belt saw a 0.9% rise. This represents a profound shift that strategic investors must heed. The key is to apply a rigorous analytical model. For instance, Savills’ research on commuter towns provides a replicable methodology, comparing average property prices and season ticket costs against the equivalent cost of owning in London, filtering for high-quality locations.
This granular analysis allows investors to identify “value” in a more sophisticated way, moving beyond just the property price to consider the total cost and quality of life for the target tenant. The following table, based on recent market analysis, gives a snapshot of the varied character and cost of different London commuter towns.
| Commuter Town | Average Property Price | Journey Time to Central London | Character |
|---|---|---|---|
| Amersham | £830,300 | ~40 minutes (Metropolitan line) | Premium ‘super-prime’ commuter hotspot |
| Berkhamsted | £751,700 | ~30 minutes (London Euston) | High demand, premium pricing |
| Wivenhoe | £477,800 | ~45 minutes (Liverpool Street) | More affordable, strong local community feel |
This data demonstrates that there is no single “best” location type; instead, there is a spectrum of risk, reward, and character. The strategic investor’s job is to select the location type that best aligns with their portfolio’s specific goals—be it tapping into the prime market in Amersham or seeking a blend of affordability and community in Wivenhoe.
Key Takeaways
- True diversification is about blending assets with non-correlated economic risks, not just different postcodes.
- A balanced portfolio combines cashflow-generating assets (e.g., HMOs) with capital-growth assets to create a self-sustaining and resilient system.
- Active management, including the regular culling of underperforming properties, is essential for maintaining portfolio quality and maximising long-term returns.
Which Property Investment Model Suits Your Income, Time, and Risk Tolerance
Ultimately, the structure of a diversified portfolio must be built upon the foundation of the investor’s personal circumstances: their available capital, income needs, time commitment, and appetite for risk. There is no one-size-fits-all model. A high-net-worth individual seeking a passive, long-term store of wealth will build a very different portfolio from a younger investor willing to be more hands-on in exchange for higher returns and the ability to replace their salary.
The models can be seen on a spectrum. At one end is the passive, standard buy-to-let (BTL) model in an established market. This offers consistency and lower management intensity but typically comes with lower yields. At the other end are more active, income-focused models like HMOs or short-term holiday lets. These strategies demand significant hands-on management (or the cost of a specialist agent) but can deliver substantially higher yields, making them suitable for those aiming to generate a primary income from property. Many experienced investors don’t choose one model but combine them, using standard BTLs as a stable base and adding a more active element like an HMO to boost overall cash flow.
The most sophisticated investors are now thinking in even longer terms, structuring their portfolios as businesses designed for generational wealth. As noted by the strategists at Commercial Trust, this represents a fundamental shift in the buy-to-let landscape:
Portfolios are being built for income, held inside limited companies, often with succession planning built in from the start, and underwritten considering a time span of twenty or thirty years, rather than five to seven.
– Commercial Trust, Strengthening your buy to let strategy for 2026 and beyond
This quote encapsulates the essence of portfolio engineering. It’s about moving from short-term speculation to the long-term, deliberate construction of a resilient financial asset. Choosing the right model—or combination of models—is the final, crucial step in aligning your property portfolio with your life goals.
The next logical step is to audit your current holdings against this strategic framework. Begin by mapping your properties by location, economic driver, and function (cash flow vs. growth) to identify your key risks and opportunities for rebalancing.